
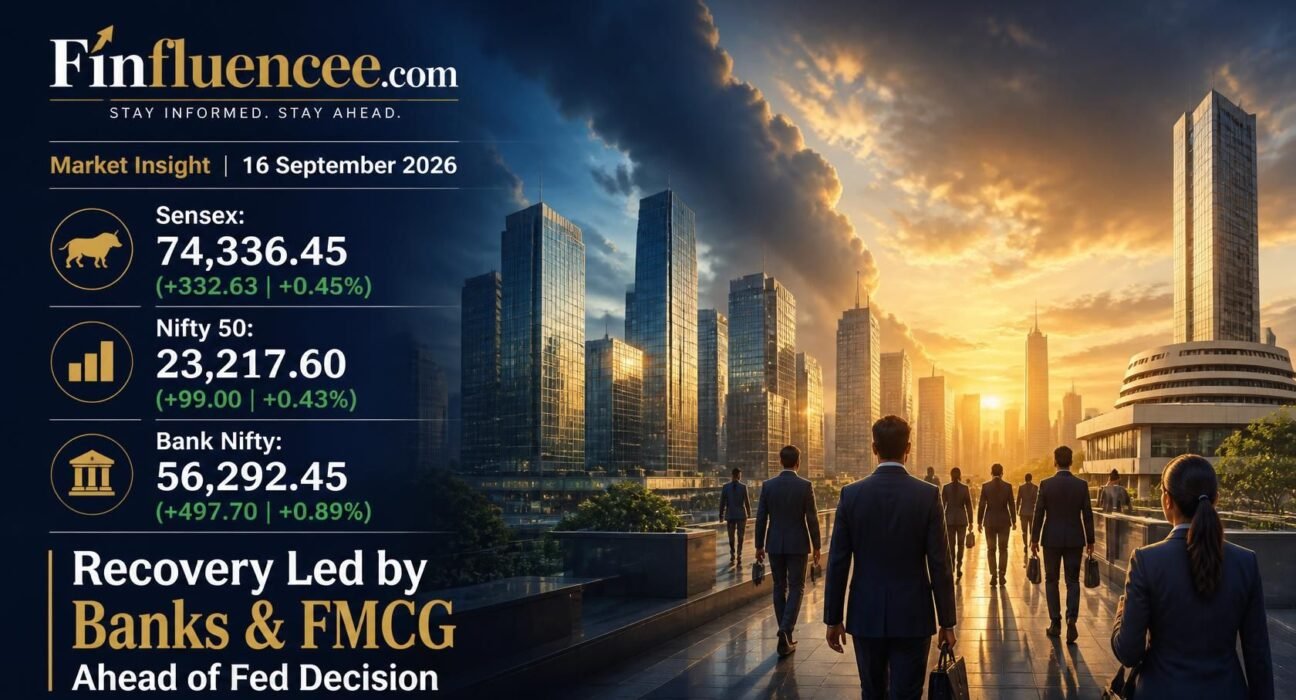
Wednesday’s session was a tale of cautious recovery after Tuesday’s brutal sell-off. Investors returned to the market looking for value in beaten-down large-cap stocks, helping benchmarks snap their two-session losing streak. Supported by positive Asian cues and expectations surrounding the U.S. Federal Reserve’s policy announcement, Indian equities managed to recover a portion of the previous day’s losses.
The recovery, however, was far from broad-based. While heavyweight banking, insurance, and FMCG stocks attracted strong buying interest, traders remained wary of elevated crude oil prices and persistent foreign institutional selling. Brent crude continued hovering near $108 per barrel, keeping inflation concerns alive and limiting aggressive risk-taking.
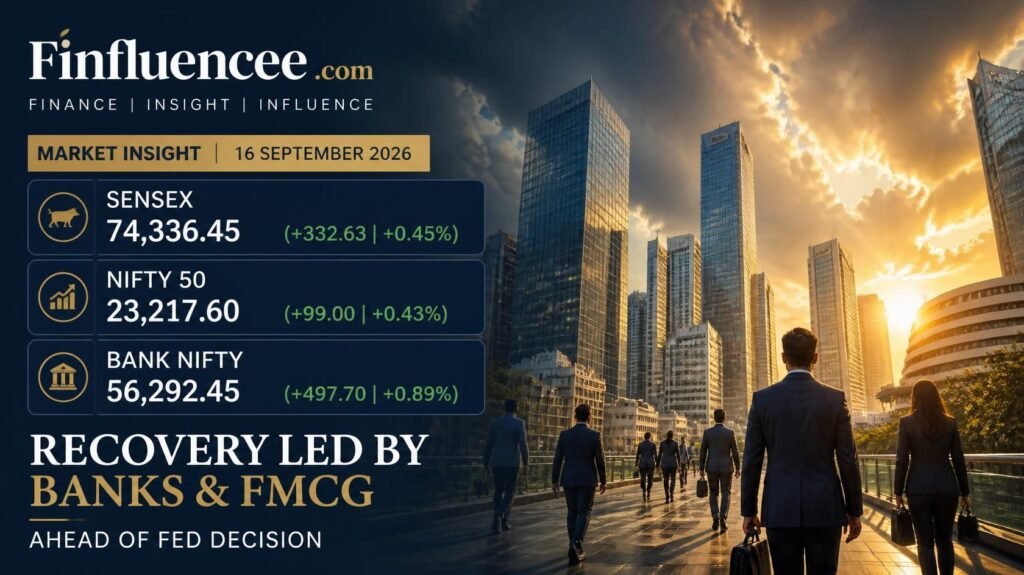
The Sensex closed at 74,336.45, gaining 332.63 points (+0.45%), while the Nifty 50 ended at 23,217.60, up 99 points (+0.43%). The rebound helped Nifty reclaim the psychologically important 23,200 level after Tuesday’s sharp breakdown.
Sectorally, the market witnessed a clear rotation toward defensive. FMCG, PSU Banks, and Private Banks emerged as leaders, while IT stocks faced profit booking after their recent out performance. Broader markets remained subdued, indicating that the day’s gains were largely driven by index heavyweights rather than widespread participation.
In essence, 16 September was a day of stabilization rather than celebration. Markets recovered, but investors continued to tread carefully as global monetary policy, crude prices, and institutional flows remained key risks.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 74,336.45 | +332.63 | +0.45% |
| Nifty 50 | 23,217.60 | +99.00 | +0.43% |
| Bank Nifty | 56,226 | +497.70 | +0.89% |
Sector Performance
Out-performers:
- FMCG (+1.82%) led gains as investors rotated toward defensive consumption stocks.
- PSU Bank (+1.27%) continued to attract buying interest.
- Private Bank (+0.73%) strengthened benchmark support.
- SBI Life, HDFC Life, ITC, Axis Bank, and SBI featured among the session’s major gainers.
Under performers:
- IT (-1.79%) witnessed profit booking.
- Pharma (-0.13%) ended marginally lower.
- TCS, Infosys, Wipro, and Tech Mahindra remained under pressure.
Institutional Flow
- FIIs: Net Sell ₹2,977.86 crore.
- DIIs: Net Buy ₹2,686.05 crore.
Insight: Domestic institutional buying once again cushioned the market from a deeper decline. However, the continuation of FII selling for a fifth consecutive session highlights lingering concerns about global liquidity, rising yields, and elevated energy prices.
Technical Structure for Thursday (17 Sept 2026)
NIFTY 50
- Support: 23,100 – 23,000
- Resistance: 23,300 – 23,500
- Trend Read: Recovery attempt underway; stronger momentum only above 23,300. Sustaining beyond 23,500 could trigger short covering.
BANK NIFTY
- Support: 55,800 – 55,500
- Resistance: 56,500 – 57,000
- Trend Read: Improving bias led by PSU and private banks, but confirmation requires sustained strength above resistance.
Options View — Neutral to Positive
- Max Pain: Around 23,200, aligning closely with Wednesday’s close.
- Significant support appears around the 23,000 strike, where traders are expected to defend positions.
- Immediate resistance remains concentrated near 23,500.
Insight: Options positioning indicates that traders expect consolidation above 23,000, though volatility may remain high following the U.S. Federal Reserve decision.
Strategy — How to Navigate Now
- Intraday / Option Buyers: Focus on banking, insurance, and FMCG stocks showing relative strength.
- Swing Traders (1–3 Weeks): Maintain selective exposure while monitoring Fed commentary and crude oil trends.
- Long-Term Investors: Continue systematic accumulation in quality large-cap financials and consumption plays.
Quick Reference — Levels for Workflow (17 Sept 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 23,100–23,000 | 23,300–23,500 | Below 23,000 |
| Bank Nifty | 55,800–55,500 | 56,500–57,000 | Below 55,500 |
Final Take
16 September delivered the rebound that many investors were hoping for after Tuesday’s sharp sell-off. Banks, insurance companies, and FMCG stocks took charge, helping benchmarks regain lost ground and pushing Nifty back above 23,200. However, the recovery was largely concentrated in heavyweight stocks, while broader market participation remained lukewarm.
Going forward, markets will be sensitive to:
- U.S. Federal Reserve policy outcome and guidance.
- Brent crude remaining near $108/bbl and its inflation impact.
- Persistent FII selling versus DII support.
Until Nifty decisively crosses 23,300–23,500 and broader markets begin to participate meaningfully, traders should remain selective rather than aggressively bullish.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI‑registered financial adviser before making any investment or trading decisions. Market conditions can change rapidly, and past performance does not guarantee future results.