
Thursday’s trading session showed resilience in Indian equities despite a challenging global backdrop. Traders started the day digesting the U.S. Federal Reserve’s surprise rate hike, which triggered weakness in several global markets and renewed concerns about liquidity conditions. Yet buying emerged in select domestic sectors, helping the Nifty hold firm.
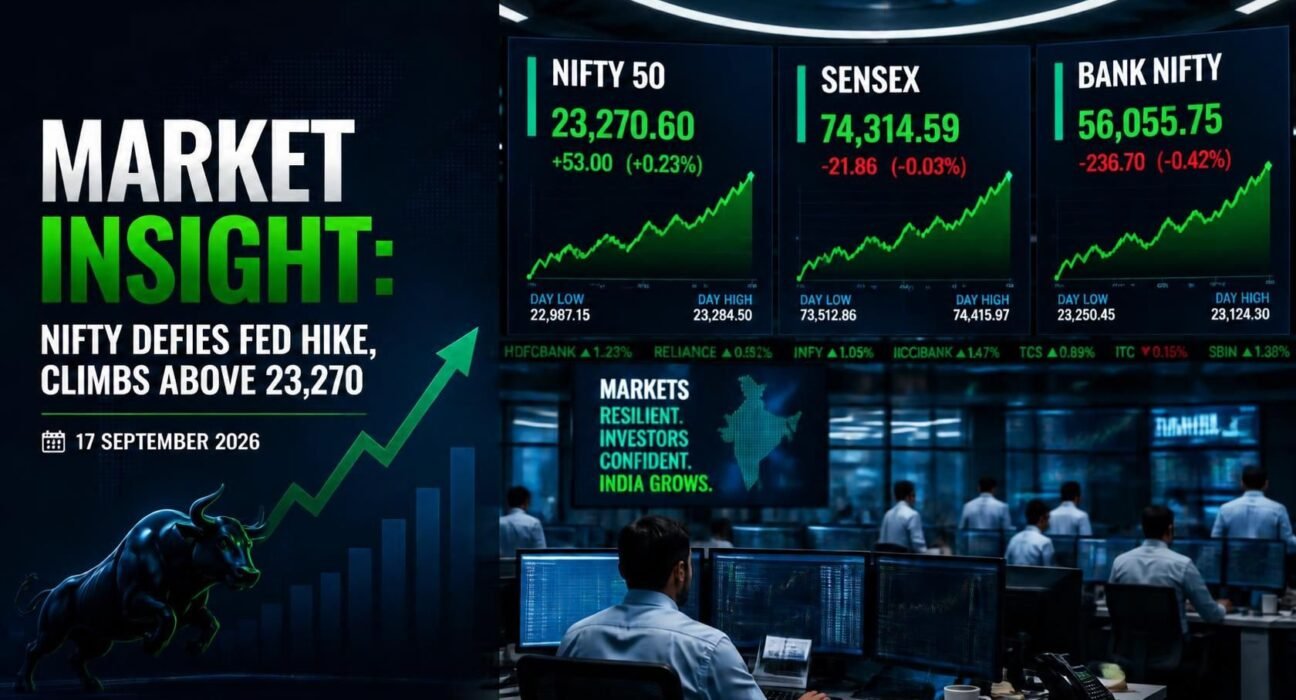
As liquidity concerns persisted, Market Insight: Nifty Tops 23,270 Despite Fed Hike captured the mood. Gains broadened across sectors as traders awaited further cues from U.S. data. The Sensex, meanwhile, finished near flat as momentum narrowed, while banking and IT names led the return.
Unlike Wednesday’s rebound, which was primarily driven by defensive heavyweights, Thursday’s advance was broader and more diversified. Strong buying emerged in realty, pharma, auto, and metal counters, reflecting renewed confidence in domestic growth-oriented sectors. Broader markets significantly outperformed benchmark indices, with both mid-cap and small-cap segments posting healthy gains, indicating improving risk appetite beyond index constituents.
The Federal Reserve’s 25-basis-point rate hike remained the dominant global talking point throughout the day. However, easing crude oil prices provided some relief to investors. Brent crude slipped closer to the $103-$104 per barrel zone after reports of additional supply availability, helping reduce immediate inflation concerns that had weighed on markets earlier in the week.
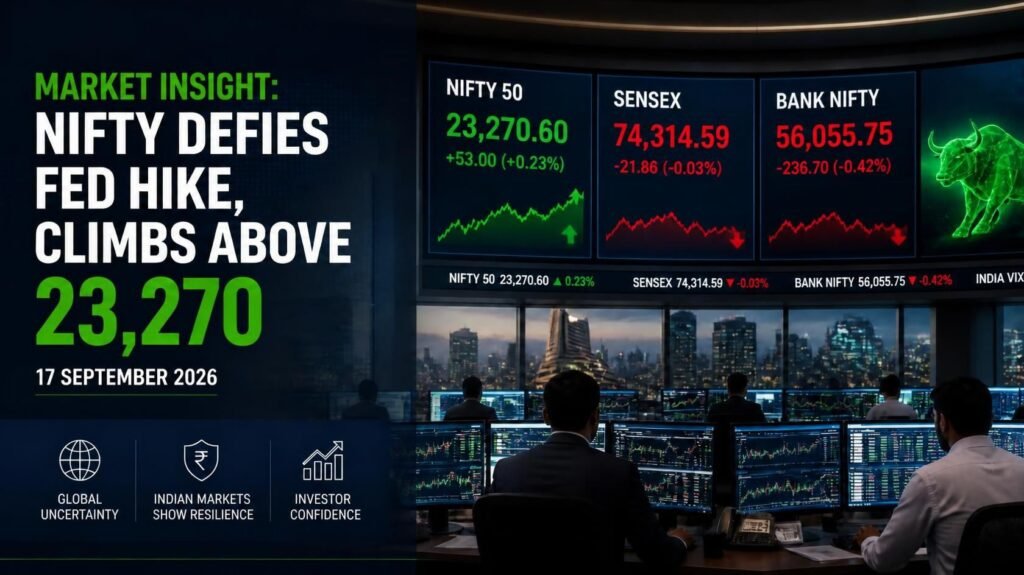
At the closing bell, the Sensex settled at 74,314.59, down 21.86 points (-0.03%), while the Nifty 50 ended at 23,270.60, gaining 53 points (+0.23%). The session showed the market’s ability to absorb global shocks while continuing to draw support from domestic institutional flows and improving breadth.
In essence, 17 September was a day of selective optimism. Global uncertainties remained intact, but participation from broader markets improved, and strength in realty, pharma, and auto stocks suggested that investors were willing to look beyond short-term global volatility.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 74,314.59 | -21.86 | -0.03% |
| Nifty 50 | 23,270.60 | +53.00 | +0.23% |
| Bank Nifty | 56,055.75 | -236.70 | -0.42% |
Sector Performance
Outperformers:
- Realty (+1.45%) emerged as the strongest-performing sector of the day.
- Pharma (+1.5%+) witnessed substantial buying interest.
- Auto (+0.99%) extended its recovery momentum.
- Metal (+0.94%) benefited from improving risk sentiment.
- HDFC Life, SBI Life, Tata Motors, Tata group stocks, and several realty counters featured among key gainers.
Underperformers:
- Banking Stocks remained under pressure and prevented a stronger index rally.
- HDFC Bank, ONGC, Titan, and select large-cap financial names witnessed profit booking.
- Insurance and domestic sectors outperformed while traditional banking heavyweights lagged.
Institutional Flow
FIIs:
Net Sell: ₹2,032.61 crore on 16 September settlement data.
DIIs:
Net Buy: ₹3,908.23 crore.
Insight:
Domestic institutional investors absorbed foreign selling pressure.
DII buying nearly doubled FII outflows, helping sustain benchmark levels despite global risk-off sentiment.
Technical Structure for Friday (18 Sept 2026)
NIFTY 50
- Support: 23,200 – 23,100
- Major Support: 23,000
- Resistance: 23,350 – 23,500
- Trend Read: Nifty has successfully held above 23,200 and continues to form a recovery structure. Sustaining above 23,300 may trigger fresh momentum toward 23,500.
BANK NIFTY
- Support: 56,000 – 55,800
- Resistance: 56,500 – 57,000
- Trend Read: Banking remains the missing piece in the current recovery. A move above 56,500 would improve broader market conviction.
Options View — Mildly Positive
- Immediate support continues around the 23,000 strike.
- Significant call writing is expected near 23,500, creating a near-term resistance ceiling.
- Holding above 23,200 keeps the short-term structure constructive.
- Broadening market participation improves the probability of range expansion to the upside.
Insight:
Options data and price action together suggest that traders are shifting from a defensive stance toward cautious optimism.
However, volatility linked to global central bank commentary could keep intraday swings elevated.
Strategy — How to Navigate Now
Intraday / Option Buyers
- Focus on Pharma, Realty, Auto, and selective Metal stocks showing relative strength.
- Avoid aggressive bullish positioning near key resistance zones.
Swing Traders (1–3 Weeks)
- Continue accumulating fundamentally strong stocks in outperforming sectors.
- Monitor crude oil movements and FII behavior closely.
Long-Term Investors
- Maintain staggered accumulation in quality large-cap financials, healthcare, and consumption businesses.
- Use volatility arising from global events as an opportunity rather than a threat.
Quick Reference — Levels for Workflow (18 Sept 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 23,200–23,100 | 23,350–23,500 | Below 23,000 |
| Bank Nifty | 56,000–55,800 | 56,500–57,000 | Below 55,800 |
Final Take
Nifty Tops 23,270 Despite Fed Hike shows a steady market as global investors digest the Federal Reserve rate hike. The Sensex ended almost unchanged. The Nifty extended its recovery, and broader markets outperformed, indicating improving domestic sentiment. Realty, pharma, auto, and metal stocks led, signaling a healthy rotation away from the narrow defensive rally earlier in the week.
Going forward, markets will closely track:
- Post-Fed global market reaction and bond yields.
- Crude oil’s movement after its recent decline toward the $103-$104 range.
- Continued FII selling versus strong DII support.
- Whether Nifty can sustain above 23,300 and challenge the important 23,500 resistance zone.
The market is no longer in panic mode. It has not yet entered a decisive bullish phase either. Sustained buying in broader markets and renewed participation from banking stocks would provide the strongest confirmation that the current recovery has further room to extend.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI-registered financial adviser before making any investment or trading decisions.