
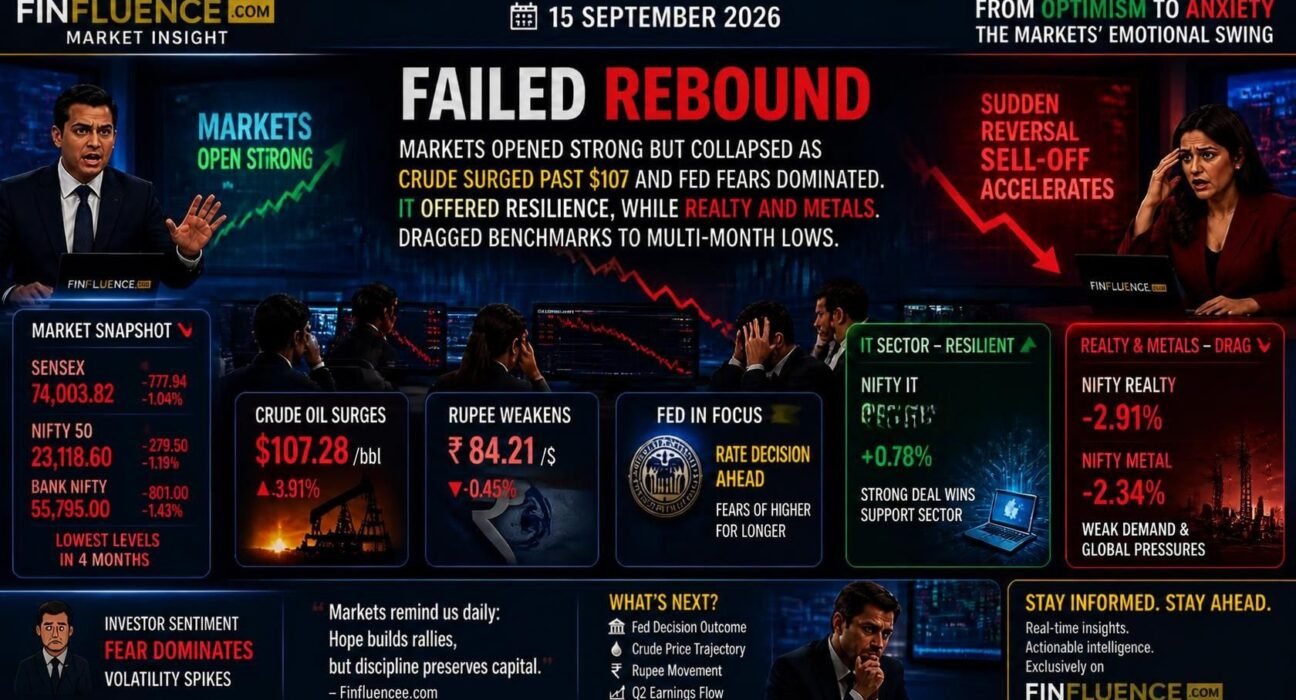
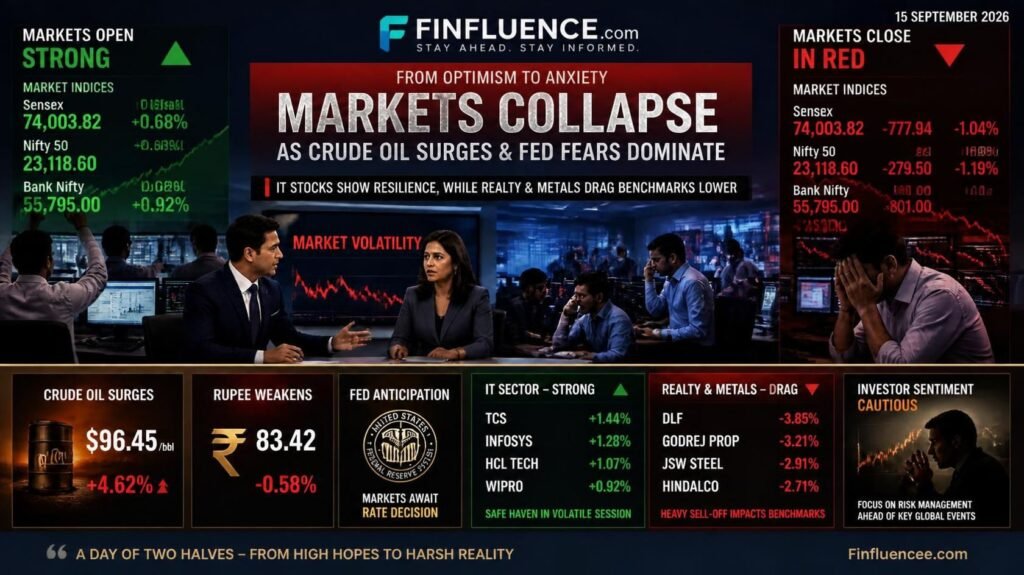
Tuesday’s session was a classic case of failed optimism. After the Ganesh Chaturthi holiday, markets opened with a strong gap‑up, buoyed by global cues and early buying in frontline stocks. The Sensex surged nearly 588 points in opening trades, and the Nifty briefly crossed 23,570, raising hopes of a rebound from last week’s weakness.
However, the rally proved short‑lived. As the day progressed, Brent crude spiked to $107.7/bbl, its highest in months, reigniting inflation fears. Simultaneously, US Treasury yields hovered near multi‑year highs, keeping global investors on edge ahead of the Federal Reserve’s policy decision. These twin pressures triggered heavy profit‑taking across sectors, erasing morning gains and pushing benchmarks to fresh five‑month lows.
The Sensex eventually closed 778 points lower at 74,003 (-1.04%), while the Nifty slipped 279 points to 23,118 (-1.19%), breaking below the crucial 23,150 support zone. The Bank Nifty fell 801 points (-1.43%) to 55,795, reflecting weakness in financials.
Sectorally, realty, metals, and chemicals bore the brunt of selling, while IT stocks offered rare resilience, with HCL Tech and Infosys posting strong gains. Broader markets underperformed sharply, with midcaps down 2.12% and smallcaps down 2.43%, underscoring risk aversion among retail investors.
Currency markets mirrored the stress: the Rupee weakened to ₹95.92/$, its lowest in over a month, pressured by strong dollar demand from oil importers. Volatility spiked, with India VIX jumping nearly 8% to 13.27, signaling heightened nervousness ahead of the Fed’s policy outcome.
In essence, 15 September was a day of dashed hopes — early optimism gave way to global macro realities, leaving investors cautious and defensive.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 74,003.82 | -777.94 | -1.04% |
| Nifty 50 | 23,118.60 | -279.50 | -1.19% |
| Bank Nifty | 55,795.00 | -801.00 | -1.43% |
| India VIX | 13.27 | +7.99% | — |
Sector Performance
- Outperformers:
- IT (+2.2%) — HCL Tech (+3.9%), Infosys (+3.6%), Tech Mahindra (+2.3%).
- HDFC Bank (+1.2%) offered resilience.
- Underperformers:
- Realty (-4%), Metals (-3.1%), Chemicals (-2.8%).
- Bharat Electronics (-6%), Adani Enterprises (-3.5%), M&M (-1.1%).
Institutional Flow
- FIIs: Net sell ~₹930.9 crore.
- DIIs: Net buy ~₹1,968.2 crore. Insight: Domestic institutions cushioned the fall, but persistent FII outflows reflect global risk aversion.
Technical Structure for Wednesday (16 Sept 2026)
NIFTY 50
- Support: 23,050 – 22,950
- Resistance: 23,250 – 23,280
- Trend Read: Weak bias; recovery only if 23,280 is reclaimed.
BANK NIFTY
- Support: 55,700 – 55,500
- Resistance: 56,400 – 56,600
- Trend Read: Bearish; strength only above 56,400.
Options View — Bearish Bias
- PCR: ~0.72 (bearish).
- Max Pain: 23,200. Insight: Options data signals downside bias unless Nifty sustains above 23,250.
Strategy — How to Navigate Now
- Intraday / Option Buyers: Focus on IT longs; avoid realty and metals.
- Swing Traders (1–3 Weeks): Defensive positioning advised; watch Fed outcome.
- Long-Term Investors: Continue SIPs; accumulate defensives and infra selectively.
Quick Reference — Levels for Workflow (16 Sept 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 23,050–22,950 | 23,250–23,280 | Below 22,950 |
| Bank Nifty | 55,700–55,500 | 56,400–56,600 | Below 55,500 |
Final Take
15 September was a failed rebound day: early optimism gave way to heavy selling as crude surged and Fed fears dominated. IT stocks offered resilience, but realty and metals dragged benchmarks to five‑month lows.
Going forward, markets will be sensitive to:
- US Fed policy (Sept 16) and rate guidance.
- Crude trajectory above $107/bbl and Middle East tensions.
- Institutional flows — whether DIIs can continue to absorb FII selling.
Until Nifty decisively reclaims 23,280 and Bank Nifty sustains above 56,400, caution should prevail.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI‑registered financial adviser before making any investment or trading decisions.