
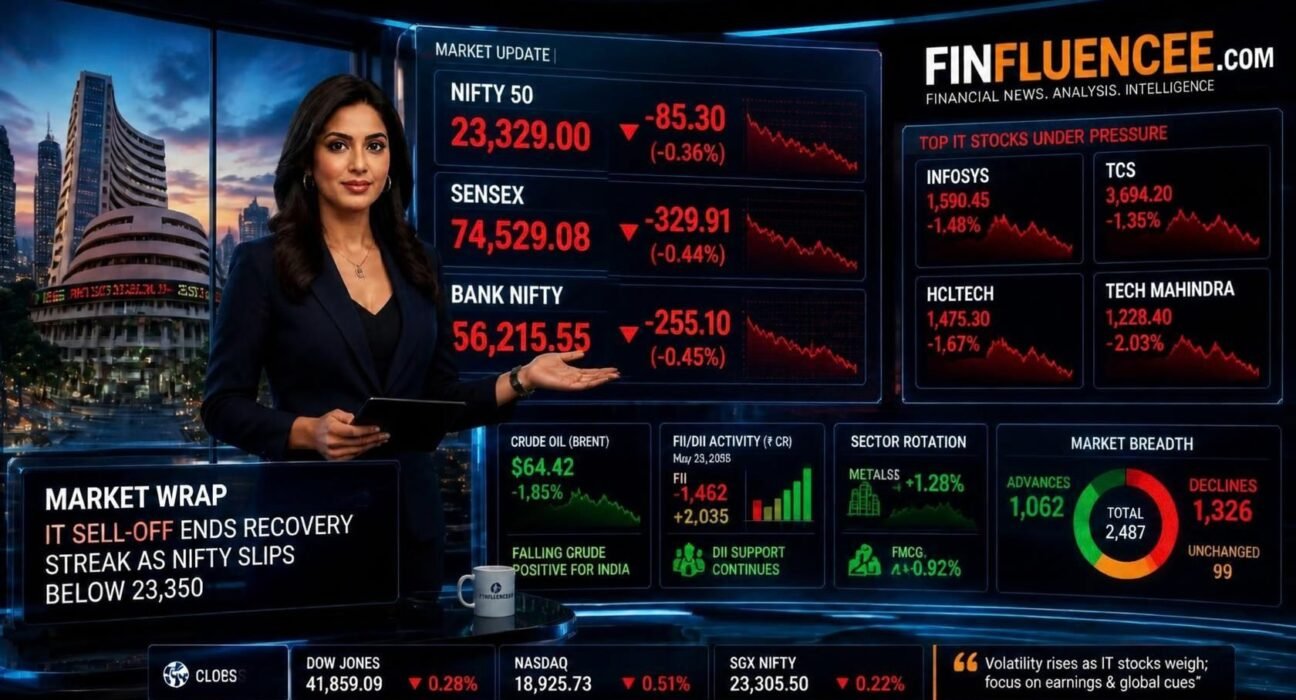
Indian equities surrendered early gains on Tuesday as persistent selling in information technology stocks overshadowed positive global cues and continued weakness in crude oil prices. The trading session began on a constructive note, with benchmark indices opening higher amid improving risk sentiment across global markets and declining bond yields. However, optimism faded as sellers re-emerged in technology and financial stocks during the second half of the session, dragging benchmarks into negative territory.
The market entered Tuesday’s session after Monday’s strong rebound, but investors struggled to extend the momentum. While lower crude oil prices generally support India’s macroeconomic outlook by easing inflation concerns and reducing import costs, traders remained cautious ahead of potential diplomatic developments involving the United States and Iran at the United Nations General Assembly. The uncertain geopolitical backdrop encouraged profit-booking in several sectors that had witnessed recent gains.
Technology stocks emerged as the biggest drag on market sentiment. Major IT companies witnessed selling pressure after brokerage commentary highlighted subdued demand conditions and concerns about medium-term earnings growth. The weakness spread across frontline technology names, causing the Nifty IT index to underperform broader markets. Financial stocks also contributed to the decline, limiting support from defensive sectors.
Unlike Monday’s session, broader market participation remained weak. Mid-cap and small-cap indices also closed lower, indicating that investors preferred caution over aggressive risk-taking. Realty stocks showed relative resilience, while energy-linked counters benefited from sector-specific buying. However, market breadth gradually deteriorated as the session progressed, reflecting the lack of conviction among buyers.
Institutional flows presented a mixed picture. Foreign investors returned to the selling side, while domestic institutions continued their strong accumulation strategy. The divergence once again highlighted the role of domestic liquidity in reducing the impact of foreign outflows on Indian equities.
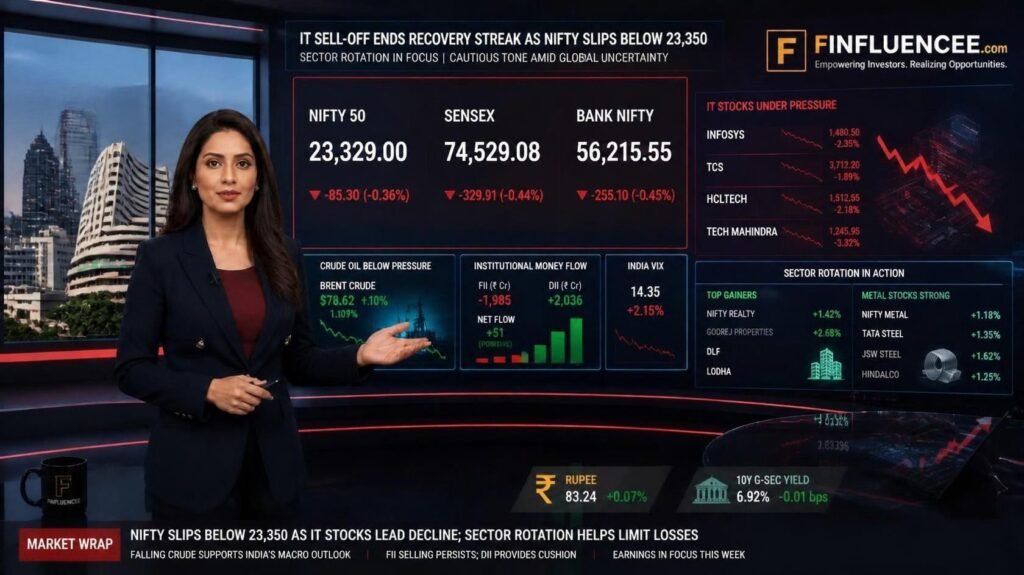
At the closing bell, the Sensex settled at 74,529.08, down 329.91 points (-0.44%), while the Nifty 50 declined 85.30 points (-0.36%) to close at 23,329.00. Bank Nifty ended at 56,215.55, losing 255.10 points (-0.45%), reflecting weakness across the financial space. The session marked a pause in the market’s recovery journey and reinforced the importance of sector-specific leadership for sustaining upside momentum.
In essence, 22 September was a session of profit-booking and sector rotation. Falling crude prices remained supportive, but concerns surrounding IT earnings, foreign outflows, and near-term global uncertainty kept buyers defensive.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 74,529.08 | -329.91 | -0.44% |
| Nifty 50 | 23,329.00 | -85.30 | -0.36% |
| Bank Nifty | 56,215.55 | -255.10 | -0.45% |
Sector Performance
Outperformers:
- Realty was among the strongest performing sectors despite broader market weakness.
- Coal India emerged as one of the top gainers within the Nifty pack.
- Metal stocks displayed relative strength compared to the broader market.
- InterGlobe Aviation, Titan and Dr. Reddy’s featured among notable gainers.
Underperformers:
- IT remained the weakest sector of the day.
- Infosys, TCS, HCLTech and Tech Mahindra remained under pressure.
- Financial stocks witnessed profit-booking after recent gains.
- Consumer-facing names such as Nestlé India and Tata Consumer underperformed.
Institutional Flow
FIIs: Net Sell ₹576.20 crore.
DIIs: Net Buy ₹2,797.27 crore.
Insight:
Domestic institutions once again absorbed foreign selling pressure. The substantial DII inflows continue to act as an important stabilizing force for Indian equities, preventing sharper declines despite periodic FII withdrawals.
Technical Structure for Wednesday (23 Sept 2026)
NIFTY 50
- Support: 23,250 – 23,200
- Major Support: 23,000
- Resistance: 23,450 – 23,500
- Trend Read: Nifty slipped below 23,350 but continues to hold above the key 23,200 support region. A sustained move above 23,450 could revive bullish momentum, while a breach of 23,200 may intensify selling pressure.
BANK NIFTY
- Support: 56,000 – 55,800
- Resistance: 56,500 – 56,800
- Trend Read: Banking stocks paused after recent strength. The index needs to reclaim 56,500 to restore near-term bullish momentum.
Options View — Neutral to Mildly Cautious
- Put support remains concentrated around the 23,000 zone.
- Call writers are active near the 23,500 strike.
- Volatility remains relatively contained despite Tuesday’s decline.
- Traders continue to prefer stock-specific opportunities over aggressive index exposure.
Insight:
The options structure suggests consolidation rather than panic. Unless Nifty breaks below the 23,200 range, traders are likely to continue viewing declines as opportunities for selective accumulation.
Strategy — How to Navigate Now
Intraday / Option Buyers
- Focus on stocks showing relative strength despite market weakness.
- Avoid aggressive IT longs until selling pressure subsides.
- Trade with strict stop-losses given sectoral rotation.
Swing Traders (1–3 Weeks)
- Continue selective accumulation in quality banking, pharma, and consumption names.
- Monitor FII activity and global market trends.
- Use declines to build exposure gradually rather than chasing rallies.
Long-Term Investors
- Remain disciplined with staggered investments.
- Continue focusing on business quality and earnings visibility.
- Treat volatility as an opportunity rather than a threat.
Quick Reference — Levels for Workflow (23 Sept 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 23,250–23,200 | 23,450–23,500 | Below 23,000 |
| Bank Nifty | 56,000–55,800 | 56,500–56,800 | Below 55,800 |
| Sensex | 74,200–74,000 | 75,000 | Below 73,800 |
Final Take
Tuesday’s session reminded investors that the market recovery remains fragile and sector-dependent. Despite continued relief from falling crude oil prices and supportive domestic liquidity, technology stocks and foreign institutional selling weighed heavily on sentiment. The decline in Nifty and Bank Nifty does not yet damage the broader recovery structure, but it signals that buyers remain selective rather than fully convinced.
Going forward, markets will closely track:
- Developments surrounding U.S.-Iran diplomatic talks.
- Crude oil price trends and inflation implications.
- Continued foreign institutional activity.
- Recovery prospects for the IT sector.
- Nifty’s ability to defend the 23,200 support zone.
While the near-term outlook remains constructive above key support levels, traders may need patience as the market navigates earnings concerns, global uncertainties, and sector rotation.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI-registered financial adviser before making any investment or trading decisions.