Indian equity markets paused after Tuesday’s powerful rebound, with benchmark indices closing lower on Wednesday as investors booked profits and remained cautious amid elevated crude oil prices, persistent foreign institutional selling, and weakness in financial and pharma stocks. Although Information Technology shares continued to attract buying following strong earnings momentum, their gains were insufficient to offset broad-based pressure across key sectors.
The market opened on a mixed note and briefly attempted to sustain Tuesday’s recovery. However, profit-taking in financials, auto, pharma, and realty stocks gradually dragged indices lower through the session. Rising Brent crude prices above $106 per barrel and continued FII selling sentiment kept investors cautious despite strength in select defensive and technology names.
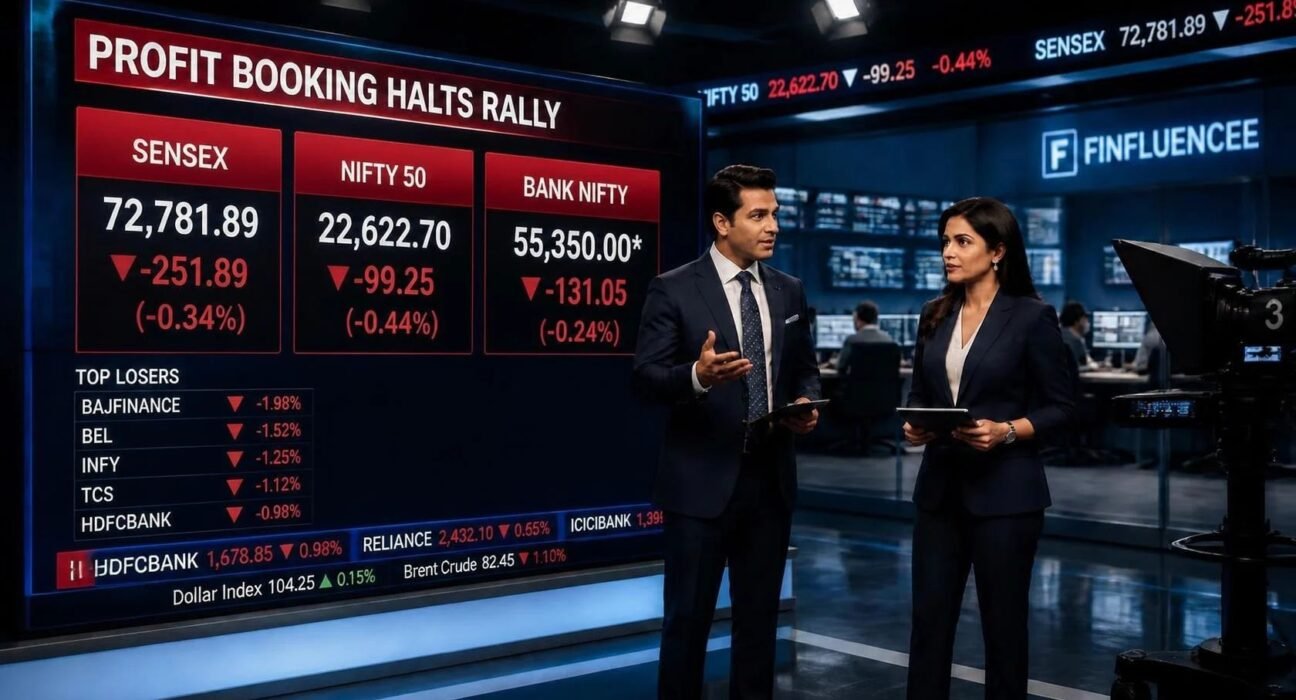
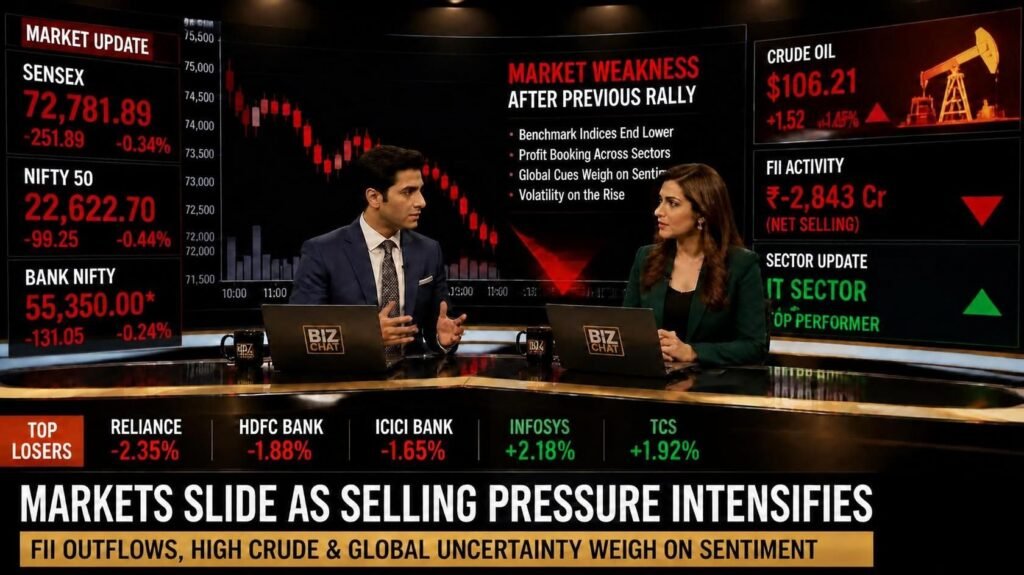
The Nifty 50 declined 99.25 points (-0.44%) to close at 22,622.70, while the Sensex fell 251.89 points (-0.34%) to settle at 72,781.89. Bank Nifty also witnessed mild pressure, ending below the 55,500 zone as banking stocks underperformed.
Technology stocks remained the primary source of resilience. Infosys, TCS, Tech Mahindra, and HCL Technologies continued to attract buying following strong quarterly earnings expectations and improving global technology sentiment. FMCG stocks also gained support as investors rotated towards defensive sectors amid uncertainty.
However, Pharma, Financial Services, Auto, Realty, and Metals emerged as key laggards. Selling pressure intensified in Shriram Finance, HDFC Life, Bajaj Finance, SBI Life, and Mahindra & Mahindra, contributing significantly to benchmark weakness. Market participants remained concerned about imported inflation risks due to rising crude oil prices and the impact of continuing FII outflows.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 72,781.89 | -251.89 | -0.34% |
| Nifty 50 | 22,622.70 | -99.25 | -0.44% |
| Bank Nifty | 55,350.00* | -131.05 | -0.24% |
Sector Performance
Outperformers
- IT gained approximately 1.25%, supported by earnings optimism.
- FMCG advanced around 0.94% as investors sought defensive exposure.
- Energy gained nearly 1.47%.
- Media rose close to 0.59%.
- Select consumption-oriented stocks witnessed fresh accumulation.
Underperformers
- Pharma declined about 1.47%, emerging as the worst-performing sector.
- Auto dropped roughly 0.94%.
- Realty fell around 0.87%.
- Metal index slipped approximately 0.67%.
- Financial Services witnessed notable profit booking.
Institutional Flow
FIIs: Continued their selling streak with latest confirmed outflows of approximately ₹1,305.13 crore.
DIIs: Remained supportive and purchased equities worth approximately ₹2,439.24 crore.
Insight: Domestic institutions once again absorbed foreign selling pressure. However, the market’s inability to hold Tuesday’s gains highlights the importance of reversing the ongoing FII selling trend for a sustained move higher.
Technical Structure for Thursday (15 Oct 2026)
NIFTY 50
- Support: 22,550 – 22,500
- Major Support: 22,400
- Resistance: 22,700 – 22,800
- Major Resistance: 23,000
Trend Read: Nifty remains within a broader recovery structure despite Wednesday’s decline. Holding above 22,500 remains critical for preserving bullish momentum. A move back above 22,800 would restore near-term strength.
BANK NIFTY
- Support: 55,200 – 55,000
- Major Support: 54,700
- Resistance: 55,700 – 56,000
- Major Resistance: 56,500
Trend Read: Bank Nifty continues to lag the broader market. Fresh strength is likely only above 55,700, while a break below 55,000 could increase short-term downside pressure.
Options View — Consolidation After Rally
- Strong Put writing remains concentrated around 22,500.
- Major Call writing continues near 22,800–23,000.
- Traders shifted to a wait-and-watch approach after Tuesday’s surge.
- Elevated crude oil prices remain a significant sentiment driver.
- Options data suggests consolidation rather than aggressive bearish positioning.
Insight: Derivative positioning indicates the market is digesting Tuesday’s rally rather than signaling a deeper correction. The 22,500 zone remains the key short-term support level.
Strategy — How to Navigate Thursday
Intraday / Option Buyers
- Buy selectively near support zones.
- Focus on IT and defensive FMCG stocks.
- Avoid aggressive longs if Nifty slips below 22,500.
Swing Traders (1–3 Weeks)
- Continue holding quality IT leaders.
- Maintain disciplined stop losses.
- Prefer staggered entries rather than chasing momentum.
Long-Term Investors
- Continue SIP investments.
- Use corrections for gradual accumulation.
- Stay diversified across Banking, IT, Consumption, and Healthcare.
Quick Reference — Levels for Workflow (15 Oct 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 22,550–22,500 | 22,700–23,000 | Below 22,400 |
| Bank Nifty | 55,200–55,000 | 55,700–56,500 | Below 54,700 |
| Sensex | 72,300–72,000 | 73,200–74,000 | Below 71,500 |
Final Take
Indian markets ended 14 October 2026 on a weaker note as profit booking emerged after Tuesday’s strong recovery rally. Elevated crude oil prices, persistent foreign institutional selling, and weakness in financial and pharma stocks weighed on sentiment despite continued strength in IT counters.
The broader market structure remains constructive as long as Nifty holds above the 22,500 region. However, investors will closely monitor crude oil trends, institutional flows, and ongoing earnings announcements for directional cues.
Key Factors to Watch
- Whether Nifty can defend the 22,500 support zone.
- Continuation of earnings-driven strength in IT stocks.
- FII flow trends after prolonged selling pressure.
- Brent crude movement above the $106 mark.
- Bank Nifty’s ability to reclaim 55,700–56,000.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI-registered financial adviser before making any investment or trading decisions.