Indian equities extended their decline for a second consecutive trading session on Tuesday, although benchmark indices managed to recover significantly from intraday lows and avoid a deeper correction. Markets remained under pressure for most of the day as investors continued assessing the implications of elevated crude oil prices, a weakening rupee, persistent foreign institutional selling, and rising global bond yields.
The session began on a weak note following Monday’s sharp selloff, with bears initially maintaining firm control over market direction. The Nifty slipped below 22,600 during intraday trade, while the Sensex briefly lost more than 700 points as risk sentiment remained fragile. However, selective buying emerged in pharmaceutical, healthcare, metal, and select infrastructure counters, helping benchmarks recover a substantial portion of their losses by the closing bell.
Sector rotation was clearly visible throughout the day. Defensive sectors such as pharma and healthcare attracted fresh buying interest as investors sought relative safety amid elevated volatility. On the other hand, consumer durables, auto, chemicals, realty, and information technology stocks continued to face selling pressure. The IT sector remained particularly weak as concerns over global demand and currency-related uncertainties persisted.
Broader markets also remained under pressure. The Nifty Midcap 100 and Nifty Smallcap 100 both ended lower, reflecting cautious participation beyond benchmark stocks. Nevertheless, the late-session recovery indicated that domestic investors remain active near important technical support levels, particularly around the 22,700 zone on the Nifty.
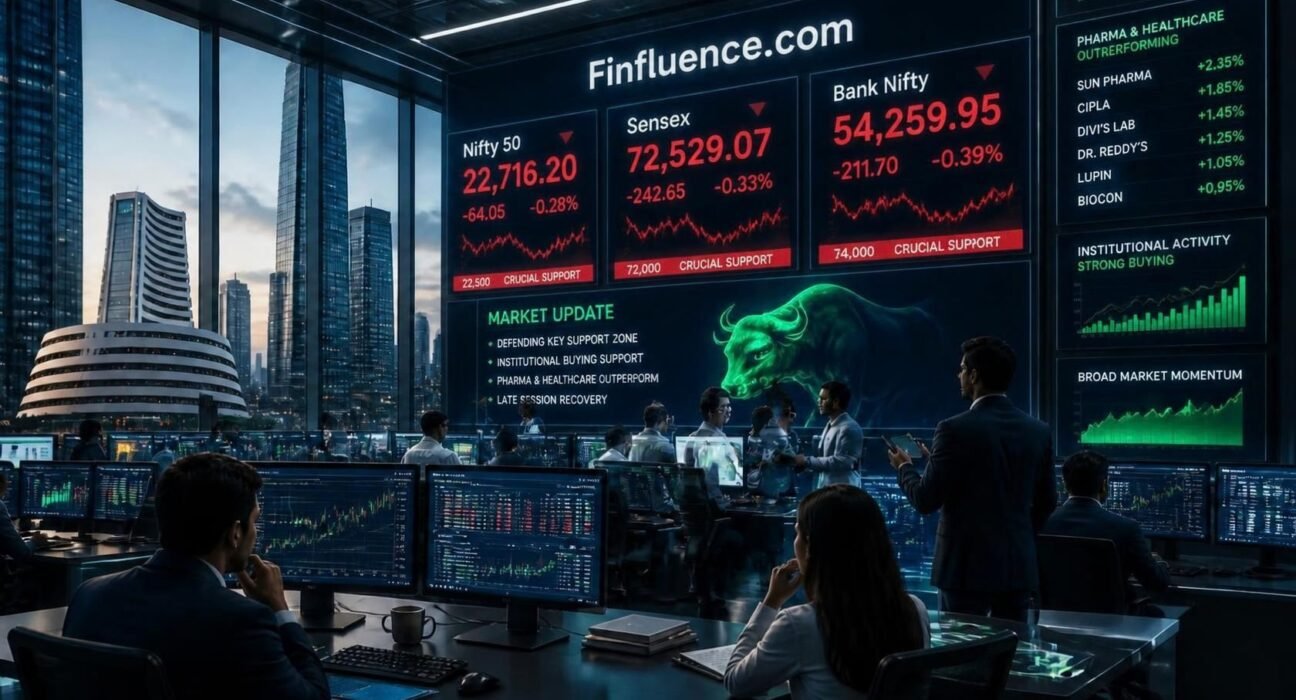
At the closing bell, the Sensex settled at 72,529.07, down 242.65 points (-0.33%), while the Nifty 50 declined 64.05 points (-0.28%) to close at 22,716.20. Bank Nifty ended at 54,259.95, down 211.70 points (-0.39%), reflecting continued weakness in the financial sector.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 72,529.07 | -242.65 | -0.33% |
| Nifty 50 | 22,716.20 | -64.05 | -0.28% |
| Bank Nifty | 54,259.95 | -211.70 | -0.39% |
Sector Performance
Outperformers
- Pharma emerged among the strongest sectors, gaining approximately 0.64%.
- Healthcare stocks attracted defensive buying interest.
- Metal stocks outperformed the broader market and ended higher.
- Adani Enterprises, Adani Ports, Dr. Reddy’s Laboratories, Sun Pharma, and Infosys featured among key gainers.
Underperformers
- Chemicals were among the weakest sectors, declining about 2.31%.
- Auto stocks remained under pressure, falling around 1.33%.
- IT continued to witness selling, losing roughly 1.48%.
- Titan, Wipro, HCL Technologies, Apollo Hospitals, and Tech Mahindra were among the major laggards.
Institutional Flow
FIIs: Net Sell ₹5,353.22 crore on 28 September 2026.
DIIs: Net Buy ₹5,189.02 crore on 28 September 2026.
Insight: Institutional flows highlight the ongoing battle between foreign and domestic investors. While FIIs continue reducing exposure amid global uncertainties and elevated crude prices, domestic institutions remain aggressively supportive. The relatively small gap between FII selling and DII buying suggests that domestic money is acting as an important stabilizing force near market support zones.
Technical Structure for Wednesday (30 Sept 2026)
NIFTY 50
- Support: 22,700 – 22,650
- Major Support: 22,500
- Resistance: 22,850 – 22,900
- Major Resistance: 23,000
Trend Read: Nifty managed to defend the crucial 22,700 support area despite heavy intraday volatility. The broader trend remains weak, but a close above 22,900 could improve short-term sentiment.
BANK NIFTY
- Support: 54,200 – 54,000
- Major Support: 53,500
- Resistance: 54,600 – 54,900
- Major Resistance: 55,300
Trend Read: Bank Nifty remains under pressure after Monday’s breakdown. Sustaining above 54,200 will be important to prevent a deeper correction.
Options View — Cautiously Bearish
- Market participants continue defending the 22,700 region.
- Significant resistance remains near 23,000.
- Volatility is elevated due to crude oil and geopolitical developments.
- Positioning still favors consolidation with a negative bias.
Insight: Options activity indicates that traders are attempting to stabilize positions near support levels, but confidence remains limited. A decisive move above 23,000 is likely required before a stronger bullish outlook can emerge.
Strategy — How to Navigate Now
Intraday / Option Buyers
- Focus on stocks showing defensive relative strength.
- Avoid aggressive counter-trend trades.
- Use strict stop-loss discipline due to elevated volatility.
Swing Traders (1–3 Weeks)
- Prefer pharma, healthcare, and selective metal stocks.
- Avoid weak momentum sectors until stability returns.
- Track crude oil and institutional flows closely.
Long-Term Investors
- Continue phased accumulation.
- Use market weakness to build positions in quality businesses.
- Remain focused on long-term fundamentals rather than short-term volatility.
Quick Reference — Levels for Workflow (30 Sept 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 22,700–22,650 | 22,850–23,000 | Below 22,500 |
| Bank Nifty | 54,200–54,000 | 54,600–54,900 | Below 53,500 |
| Sensex | 72,300–72,000 | 73,000–73,300 | Below 71,800 |
Final Take
The market remained under pressure on 29 September, but the ability of benchmark indices to recover sharply from their intraday lows offers a modest positive signal. Nifty successfully protected the critical 22,700 region, while domestic institutional buying continued to absorb substantial foreign selling pressure.
Going forward, markets will closely monitor:
- Crude oil price movements near the $100 zone.
- Continued FII selling activity.
- Rupee movement against the U.S. dollar.
- Nifty’s ability to sustain above 22,700.
- Whether defensive sectors continue attracting institutional money.
While the broader trend remains cautious, Tuesday’s recovery from the lows suggests buyers have not completely stepped away. The next few sessions will determine whether the market can stabilize or whether the correction extends further.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI-registered financial adviser before making any investment or trading decisions.