Indian equities concluded September on a subdued note, extending their recent losing streak as persistent foreign fund outflows, elevated global bond yields, and lingering concerns surrounding crude oil prices continued to limit investor confidence. Although benchmark indices avoided a major selloff during the final trading session of the month, the inability of the market to sustain intraday recoveries highlighted the fragile nature of current sentiment.
The trading session remained highly volatile from start to finish. Markets initially attempted a rebound, supported by easing crude prices and selective buying in private banking stocks. However, renewed selling in healthcare, pharma, and select heavyweight stocks gradually pushed benchmarks back into negative territory. Despite weakness in the broader market, the banking sector emerged as a notable area of strength and helped prevent a deeper decline.
The broader market painted a mixed picture. While benchmark indices ended lower, small-cap stocks displayed resilience and managed modest gains. Mid-caps remained largely flat, indicating that selective stock picking rather than broad risk appetite drove activity during the session. Investors continued rotating capital toward relatively stronger banking names while reducing exposure to sectors facing valuation and earnings concerns.
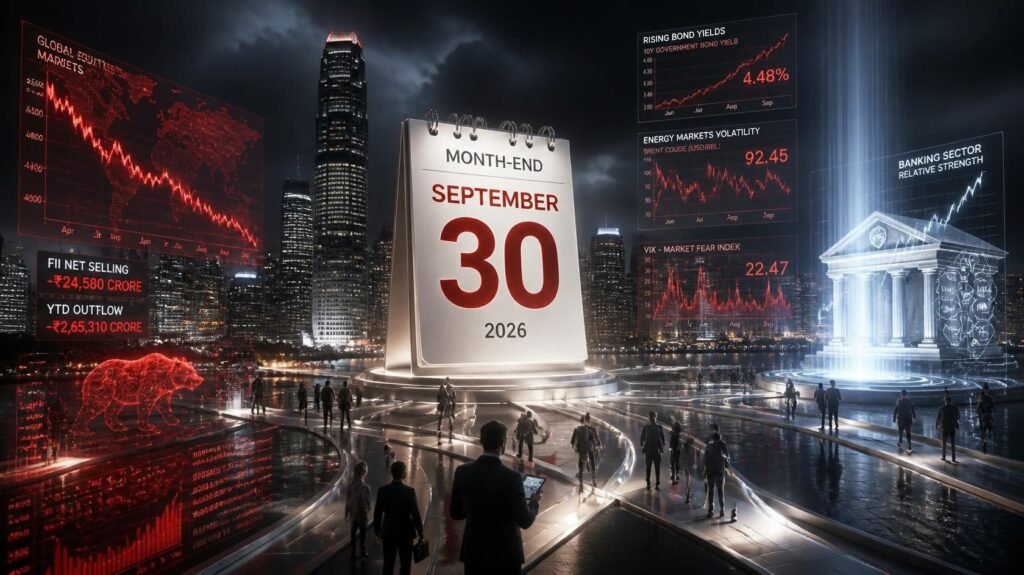
September ultimately proved challenging for Indian equities. Rising U.S. Treasury yields, volatile energy markets, and sustained foreign institutional selling pressured valuations throughout the month. The Nifty recorded one of its weakest monthly performances in years, while market participants increasingly adopted defensive positioning amid uncertain global conditions.
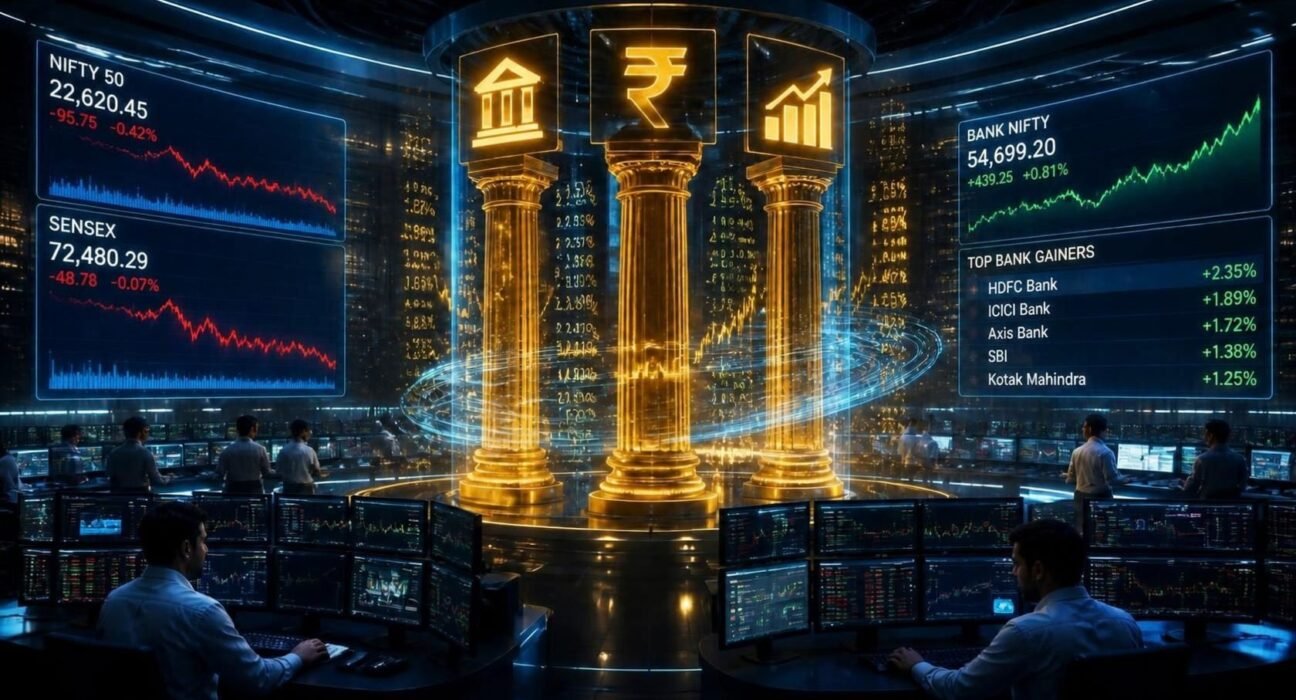
At the closing bell, the Sensex settled at 72,480.29, down 48.78 points (-0.07%), while the Nifty 50 declined 95.75 points (-0.42%) to close at 22,620.45. In contrast, the Bank Nifty gained 439.25 points (+0.81%) to finish at 54,699.20, reflecting strong buying interest in private sector lenders.
Benchmarks — Closing Snapshot
| Index | Close | Change | % Change |
| Sensex | 72,480.29 | -48.78 | -0.07% |
| Nifty 50 | 22,620.45 | -95.75 | -0.42% |
| Bank Nifty | 54,699.20 | +439.25 | +0.81% |
Sector Performance
Outperformers
- Banking emerged as the strongest sector of the session.
- ICICI Bank rose 2.38%.
- Kotak Mahindra Bank gained 2.22%.
- InterGlobe Aviation (IndiGo) advanced 1.91%.
- TCS and Tech Mahindra provided support to the IT space.
Underperformers
- Pharma declined 1.84%.
- Healthcare stocks witnessed heavy selling pressure.
- Apollo Hospitals plunged 6.63%.
- Max Healthcare fell 5.81%.
- ONGC, Adani Enterprises, and Eternal remained among major drags.
Institutional Flow
FIIs: Net Sell ₹9,980.22 crore.
DIIs: Net Buy ₹6,952.71 crore.
Insight: Foreign investors remained aggressive sellers into month-end, reflecting ongoing concerns about global liquidity conditions and elevated U.S. yields. Domestic institutions once again provided significant support, preventing the market from witnessing a sharper correction. The divergence between FII and DII activity remains one of the dominant themes driving Indian equities.
Technical Structure for Thursday (1 Oct 2026)
NIFTY 50
- Support: 22,600 – 22,550
- Major Support: 22,400
- Resistance: 22,800 – 22,900
- Major Resistance: 23,000
Trend Read: Nifty closed below 22,700 and remains under pressure. Holding above 22,600 is critical. A breakdown below that level could trigger another leg of weakness toward 22,400.
BANK NIFTY
- Support: 54,500 – 54,300
- Major Support: 54,000
- Resistance: 55,000 – 55,200
- Major Resistance: 55,500
Trend Read: Bank Nifty showed relative strength and outperformed the broader market. Sustaining above 54,500 could support further recovery.
Options View — Defensive
- Put activity is expected around the 22,500 zone.
- Strong resistance remains near 23,000.
- Traders continue maintaining a cautious stance.
- Volatility is elevated due to global macro uncertainty.
Insight: Options positioning indicates defensive sentiment. Market participants appear focused on preserving capital rather than chasing upside opportunities until volatility moderates.
Strategy — How to Navigate Now
Intraday / Option Buyers
- Prefer banking stocks showing relative strength.
- Avoid aggressive trades against prevailing trends.
- Maintain strict stop-loss discipline.
Swing Traders (1–3 Weeks)
- Focus on sectors attracting institutional buying.
- Avoid weak healthcare and pharma counters until stability returns.
- Monitor global yields and FII flows.
Long-Term Investors
- Continue staggered accumulation.
- Use corrections to build quality portfolios.
- Maintain a long-term perspective despite short-term volatility.
Quick Reference — Levels for Workflow (1 Oct 2026)
| Index | Buy on Dip Zone | Resistance | Risk Zone |
| Nifty 50 | 22,600–22,550 | 22,800–22,900 | Below 22,400 |
| Bank Nifty | 54,500–54,300 | 55,000–55,200 | Below 54,000 |
| Sensex | 72,200–72,000 | 73,000–73,300 | Below 71,800 |
Final Take
September ended on a cautious note, with benchmark indices remaining under pressure despite visible strength in banking stocks. The market continues to struggle against the headwinds of elevated global yields, foreign selling, and uncertain macro conditions. Nevertheless, aggressive domestic institutional buying and resilience in financial stocks suggest that buyers have not completely abandoned the market.
Going forward, investors will closely monitor:
- FII selling intensity.
- U.S. Treasury yield movements.
- Crude oil price stability.
- Nifty’s ability to defend 22,600.
- Continuation of banking sector leadership.
While the broader trend remains cautious, a stabilization in global macro conditions could provide the foundation for a recovery during the opening weeks of October.
Disclaimer
This Market Insight is prepared for educational and informational purposes only. It does not constitute investment advice, recommendation, or solicitation to buy/sell securities. Readers are advised to consult a SEBI-registered financial adviser before making any investment or trading decisions.